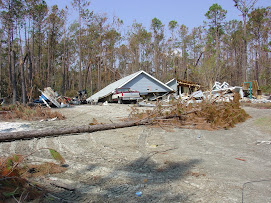
Gene Taylor's issue + answers lecture at USM Gulf Park was a well attended event. Besides Congressman Taylor, Senatorial hopeful Ronnie Musgrove, State Senator David Baria and Insurance Commissioner Mike Chaney were in attendance. While I organize my thoughts and before I give my personal impressions, I'll post the Sun Herald story along with the actions of our fellow blogger and friend Steve,
This news story contains a factual inaccuracy, HR 3121 does not repeal the McCarran Ferguson anti trust exemption. sop
Taylor asks residents to act
Wants support for multi-peril coverage
By MICHAEL A. BELL
Continuing his fierce pursuit of federal multi-peril insurance, U.S. Rep. Gene Taylor on Friday urged South Mississippians to flood senators with e-mails, letters and phone calls in support of a bill that would allow property owners to purchase both wind and flood insurance under one policy.
"We're all in this together," he told hundreds at the University of Southern Mississippi's Gulf Coast Campus.
Taylor's lecture, "The Insurance Crisis: A Case for Multi-Peril Coverage," was part of the Issues + Answers series sponsored by the school and the Sun Herald.
The U.S. House has approved multi-peril insurance. But the legislation faces heavy opposition in the Senate.
"We need our senators to champion this issue," said Taylor, who's trying to convince senators to support the addition of wind coverage to the National Flood Insurance Program.
Taylor argued insurance agents who probed the post-Katrina wreckage blamed the damage on wind. "I think the taxpayers got hosed on that," he said. "Insurance is killing us."
He said the private insurance industry made nearly $50 billion the year Katrina hit, then nearly $70 billion in 2006.
But people stuck in FEMA trailers - "42,000 little cubicles of love," he quipped - continue to grapple with recovery.
"A lot of people are hesitant to rebuild," he said. "And that's not a good thing for our country."
He argued his bill would provide peace of mind to residents that they won't have to prove wind or water caused property damage.
"You don't have that lingering feeling that 'maybe I ought to stay behind with a video camera and have some evidence'," he said.
He added his bill would no longer exempt the insurance industry from anti-trust laws.
Former Gov. Ronnie Musgrove and current Insurance Commissioner Mike Chaney attended Taylor's presentation.
Taylor's 60-minute speech was followed by a standing ovation and a Q&A session.
One woman asked how much Taylor's policy would cost if it were approved by the Senate.
"The answer is, 'We don't know,'" Taylor said, adding the coverage would be optional. "But it's got to pay for itself."
Kenneth Trawick, 76, of Gulfport called the insurance industry a "runaway group of thieves" and thanked the congressman.
Saturday, March 1, 2008
Gene Taylor Issues + Answers Lecture


Friday, February 29, 2008
Breaking: Scruggs Contempt Case in Alabama Dismissed
David Rossmiller has broke this story on his blog. Thanks to Bellesouth for the pdf of the order and heads up.
sop
Update:
I have read the order for dismissal and await a lawyer's analysis but to me it boils down to what was very apparent from reading Judge Acker's original order; the law enforcement exception contained therein is absolute and was met as demonstrated by the facts of the case. Also Judge Vinson found Judge Acker's order was poorly written:
There is some ambiguity in the wording of the order because if the first paragraph was complied with (and the documents were given to counsel for Renfroe), then as Judge Acker himself acknowledged at the March 2007 contempt hearing [see Doc. 130 at 187-88], the second paragraph would be superfluous (i.e., the Rigsbys could not further disclose, use or is appropriate materials no longer in their possession). The special prosecutors attempt to resolve this ambiguity by arguing that the second paragraph meant only that the Rigsbys “could cooperate with law enforcement by discussing with law enforcement what they knew about the documents.” See Doc. 11 at 5. This contention overlooks the nature of the object of the injunction. The second paragraph by its own terms applied to “any material described” in the first paragraph, which plainly consisted of the tangible documents themselves. Any attempt to limit the second paragraph to “mental impressions” or “recollections” must fail.....And finally the heart of the matter:
However, the fact remains that Scruggs did not violate the clear and express terms of the injunction. Again, as then-Judge (now Justice) Stephen Breyer has observed, courts must read injunctions "to mean rather precisely what they say."While Judge Vinson did cast a wary eye on the arrangement between Mr Scruggs and Mr Hood the bottom line was that issue was ancillary to the points of law. I wonder if Marsha Thompson at WLBT will now rehash the Rigsby sister's sex lives in an attempt to save face.
The injunction specifically and precisely said the documents could be given "to law enforcement officials at their request." Regardless of the subjective intent that Hood may have had when he requested the documents, the undisputed fact is that he did make such a request. The objective language of the injunction expressly authorized the law enforcement exception, and it must be recognized here. Criminal contempt under such circumstances cannot be supported under the law.
This issue has been resolved and not the way the self proclaimed cyber experts predicted. At the risk of appearing snotty such things happen to the closed and weak minds.
Our best wishes and regards go out to the Rigsby sisters for their strength in the face of this assault on their characters and reputations.
sop
Wednesday, February 27, 2008
Don’t Mess with Texas – or Connie Moran
 Big Insurance, meet Connie Moran – a Fulbright Scholar with a master’s degree in finance/economics and international commerce – the Mayor of Ocean Springs, Mississippi with all perils insurance on her mind.
Moran wants more than stories about businesses and residents having trouble rebuilding due to insurance costs, she want hard data. According to the Mississippi Press Register, she plans to provide that data to Congressman Gene Taylor.
A small town Mississippi mayor may not sound like a threat – unless you happen to have read about her accusing FEMA of “creating trailer trash” in the Seattle Times.
The mayor first gained national attention when she locked horns with FEMA, preferring the traditional and sustainable Katrina Cottages to the standard-issue mobile homes that “within 18 months create a trash-heap of trailers up for auction.”
She envisioned a neighborhood of "Katrina cottages" — tiny, yellow houses built in a Southern style, with sloped metal roofs and big front porches.
Ocean City has actually created “a planned village of 20 ‘Katrina cottages” about a mile from Ocean Springs’ downtown.”
You don’t mess with Texas or Connie Moran – if you don’t believe me, contact the Mississippi Department of Transportation and ask about that bridge they almost had to sell.
Monday, February 25, 2008
Breaking: Federal Jury Finds 5 Former Insurance Executives Guilty in Financial Manipulation Scheme
Not much time for analysis but here is the news story. sop
HARTFORD, Conn. (AP) -- Five former insurance company executives were found guilty Monday of a scheme to manipulate the financial statements of the world's largest insurance company.
The verdict came following a monthlong trial in federal court.
The defendants, four former executives of General Re Corp. and a former executive of insurance industry leader American International Group Inc., sat stone-faced as the verdict was read.
They were accused of inflating AIG's reserves through reinsurance deals by $500 million in 2000 and 2001 to artificially boost its stock price.
Reinsurance policies are backups purchased by insurance companies to completely or partly insure the risk they have assumed for their customers.
The defendants were former General Re CEO Ronald Ferguson; former General Re Senior Vice President Christopher P. Garand; former General Re Chief Financial Officer Elizabeth Monrad; and Robert Graham, a General Re senior vice president and assistant general counsel from about 1986 through October 2005.
Also charged was Christian Milton, AIG's vice president of reinsurance from about April 1982 until March 2005.
Ferguson, Monrad, Milton and Graham each face up to 230 years in prison and a fine of up to $46 million. Garand faces up to 160 years in prison and a fine of up to $29.5 million.
"This is a very sad day, not only for Ron Ferguson, but for our criminal justice system," Clifford Schoenberg, Ferguson's personal attorney, said in a statement distributed at U.S. District Court in Hartford. "I and the rest of Ron's legal team will not rest until we see him -- and justice -- vindicated."
Sunday, February 24, 2008
Yo Allstate: Florida Isn't Amused OIR Moves to Ban Allstate
Earlier this week there was some improtant developments involving Florida's battle with Allstate. As we have repeatedly noted in our continuing coverage of Allstate there is a pattern of behavior exhibited by this insurance giant of ignoring lawful subpoenas and court orders. Worse according to the Florida Office of Insurance Regulation complaint:
Encompass Floridian Insurance Company’s chief executive officer knowingly made and filed a false certification.....This charge involves a certification on the rate filing that the CEO of the operating company has reviewed the entire application. When sworn under oath the CEO of Allstate's Florida subsidiary admitted he signed the document only reviwing the execuitive summary and thus was unable to answer detailed questions by the Florida Senate committee.
To put this into context this was the type of defense by ignorance used by Ken Lay at Enron (the three wise monkeys). It resulted in CEO's and CFO's being required by Sarbanes-Oxley to affirmatively certify their companies financial information submitted to the Securities and Exchange Commission. Here is a link to Thomas Wilson certifing the last quarterly corporate financial statement and in the process doing what the CEO of his Florida subsidiary did not do, reading and certifing that an important document is accurate and complete. I now wonder if those internal controls Mr. Wilson swore were working on October 30, 2007 really are in light of the FLOIR Complaint. After all a good system of internal controls include those which insure compliance with applicable laws and regulations.
In any event here is the press release from Commissioner McCarty's office for our readers to consider. Events in Florida are heating up and as pointed out elsewhere by Mr CLS could directly tie into the shareholder derivative suit styled Fojas v. Ackerman.
Florida Insurance Commissioner Kevin McCarty today announced that the Office of Insurance Regulation (Office) has filed an administrative complaint on a non-emergency basis seeking to suspend the certificates of authority of the Allstate Companies (Allstate) to write new insurance policies in Florida.
The complaint is based in part on Allstate's failure to provide witnesses and documents as subpoenaed by the Office; falsely labeling subpoenaed documents as trade secret and falsely certifying its rate filings.
"Seeking to suspend a company's license is not something we take lightly," said General Counsel Steve Parton. "However, in light of their defiance of the Florida Insurance Code, we think it is necessary to make the point that actions such as we have seen by Allstate will not be tolerated."
Allstate was to have provided all appropriate company documents related to the Office's investigation at or before the Jan. 15 hearing. Instead, in late November, Allstate filed 51 pages of objections to the subpoenas. Allstate has been delivering documents to the Office since the Jan. 15 hearing, but has not delivered all documents requested by the subpoenas and is maintaining claims of privilege to some of the documents.
The Office has been asking for documents about Allstate's reinsurance program, its relationships with risk modeling companies, insurance rating organizations and insurance trade associations. The subpoenas also required appropriate witnesses to appear at the January hearing to be able to discuss issues that were subjects of the subpoenas.
The complaint also alleges that Allstate has violated Florida law by not properly certifying its rate filings as required by House Bill 1A, which passed in January 2007.
Filing the complaint is required under Florida law as part of the process that began when Commissioner McCarty issued the Immediate Final Order (IFO) Jan. 17, suspending Allstate from writing any new business in Florida. Allstate is expected to request an administrative hearing on the Office’s complaint. If requested, a hearing would be held at the Division of Administrative Hearings (DOAH).
An administrative law judge will hear the evidence and then make findings of fact. Commissioner McCarty could then issue a Final Order, which may include a suspension of Allstate's certificates of authority. Allstate could then appeal to the First District Court of Appeal.
The DOAH hearing is separate from the ongoing matter that Allstate initiated in the First District Court of Appeal (DCA) by filing its Jan. 17 notice of appeal of the commissioner’s IFO. That matter is still proceeding in the DCA.
The Allstate suspension was the first time the Office had suspended a company for failure to "freely" provide documents as required by Florida law.
The Order would apply to all Allstate companies on which the subpoenas were served:
Allstate
Floridian Insurance Co.
Allstate Indemnity Co.
Allstate Property &
Casualty Insurance Co.
Allstate Insurance Co.
Allstate Floridian
Indemnity Co.
Allstate Fire and Casualty Insurance Co.
Encompass
Insurance Co. of America
Encompass Indemnity Co.
Encompass Floridian
Insurance Co.
Encompass Floridian Indemnity Co. A copy of the subpoena is available
to review.
sop
Florida Again Dominates the Insurance Battle
There were two big announcements out of Florida this week, one involving Allstate and one involving State Farm. I'll tackle State Farm first since it is more complex and the most disingenuous.
Some background is in order for State Farm. When Florida created a state market for cheaper reinsurance it also mandated premium reductions for those who took advantage of the program. Two major insurers filed for rate increases after buying the state reinsurance, Allstate and State Farm. When Insurance Commissioner McCarty ordered rate hearings for the increases (rate hearings in Florida involve public sworn testimony including revealing the basis for the rate increases) State Farm backed down and instead reduced their homeowner premiums in accordance with the law. As is their custom in states where they do not get their way including here in Mississippi when we dared to litigate against them they announced they will no longer write new homeowner policies in Florida. I like Beatrice Garcia's reports on insurance news from Florida so today I've linked the Miami Herald story on this development.
In a move certain to deepen Florida's insurance crisis, State Farm Florida plans to stop writing new homeowners policies throughout the state starting Saturday.
The state's largest private insurer of homes also won't offer new renters or commercial policies in order to reduce its exposure to hurricane risk in Florida.
State Farm's current policyholders won't be affected by the move. The company will continue to renew the one million homeowners and renters policies it has in Florida.
The insurer also will continue to write new auto insurance in Florida, a far more lucrative line of insurance than property coverage. It insures more than two million vehicles.
State Farm will cease writing new homeowners policies just days before lawmakers return to Tallahassee to wrestle once again with proposals to make insurance coverage more affordable and available.
However unlike Mississippi which kowtows before these large insurance companies Florida's Office of Insurance Regulation has some arrows left in it's quiver. Contrast the Florida approach as outlined yesterday and my comment to yesterday's post of Mississippi's of letting insurers dump off coast consumers in the state wind pool:
Ed Domansky, an OIR spokesman, said that as a courtesy State Farm Florida told regulators of its plan to stop writing new homeowners policies. While OIR regulates insurance company activities in Florida, it has no authority to block State Farm's move.
Domansky said Insurance Commissioner Kevin McCarty was disappointed by State Farm's decision.
Both McCarty and OIR General Counsel Steve Parton will see if State Farm will be in compliance with a new law that requires companies to sell homeowners coverage in Florida if they sell other lines here and sell homeowners insurance elsewhere in the country.
Sen. Steve Geller, a Democrat from Cooper City, said he believes State Farm will stay within the bounds of the new law because the company will be renewing existing property insurance policies.
State Farm is trying to curtail its risk if a massive storm hits, particularly in densely populated areas such as South Florida and the Tampa-St. Petersburg area. But Geller wonders if State Farm's action could also be driven by another motive.
State Farm and Allstate are aggressive backers of a bill introduced in the Florida House of Representatives last week that would create a statewide windstorm program to write hurricane coverage throughout the state, not just along the coast.
Under that proposal, insurers could decide to write policies without hurricane coverage or still sell traditional multi-peril policies. These policies wouldn't be subject to surcharges to make up any deficits in the state-run Citizens Property Insurance, the state's largest insurer of homes and condos.
State Farm's new move ''could be a threat to get more favorable consideration'' of this bill, Geller said.
The bill faces resistance. Sen. Bill Posey, R-Rockledge and chairman of the Senate Banking and Insurance Committee, sees the bill as an "insurance industry relief bill. That's why it's a non-starter with me."
Isn't it strange that the insurance company PR departments and trade groups denounce the NFIP as a taxpayer subsidy (it is and was intended as one when it was enacted in 1969) yet expect the taxpayers to bail them out every time they hit a bump in the road? Senator Posey has it exactly right in my opinion and I hope the Florida legislature does not let these insurance companies offload their least desired risk exposures on the taxpayers while continuing to profit handsomely from other lines of business.
sop
Thursday, February 21, 2008
Breaking: Allstate Fined $250,000, Ordered to Reinstate Policies
Thanks to Mr CLS for the heads up to this Times Picayune story.
BATON ROUGE -- Insurance Commissioner Jim Donelon fined Allstate $250,000 Wednesday and ordered the state's second-largest insurer to reinstate the wind and hail coverage of several hundred customers whose policies were dropped in disregard of a key consumer-protection law.
It is the only fine that Louisiana has levied against a homeowners insurance company since Hurricane Katrina, and the fine is the maximum penalty allowed by state law.
"I'm doing that because of the continuing efforts of the company to circumvent the consumer
protections that have served us so well," Donelon said. "This statute is the law of Louisiana. It was the law of Louisiana when these policies were written, and it will be enforced."
Donelon said he has tangled with Allstate three times in the past year and a half over the company's efforts to circumvent a Louisiana consumer-protection law that makes it difficult for insurers to drop policyholders after three years, and he said he is tired of it.
In July 2006, Allstate announced plans to drop 30,000 customers in south Louisiana in a way that Donelon said would violate the three-year law, and it took five months of negotiations to get the company to take a different tack. In spring 2007, Allstate conducted cursory drive-by inspections of homes and tried to cancel hundreds of homes that it deemed "abandoned" that were actually under repair or occupied before the state Insurance Department intervened.
And most recently Allstate has been reclassifying some longtime customers as new ones so their wind and hail coverage could be dropped. Donelon said the ongoing problems with Allstate's practices led him to conclude that the company was flouting the law and needed to be penalized.
Allstate admits no wrongdoing. The suburban Chicago company said it disagrees with the Louisiana Insurance Department on its interpretation of insurance laws.
But Allstate, the sponsor of the Sugar Bowl, said in the consent agreement and stipulation signed Tuesday that it decided to settle the matter "in recognition of the catastrophic events of 2005, the continuing concern for its customers and as a gesture of goodwill."
In a news release Wednesday, Allstate said it agreed to pay the money "to avoid expenses associated with a hearing."
But Donelon said the $250,000 is indeed a fine. "In my view, absolutely," he said. "No one else has gotten close to the need for punitive action."
Cursory inspections done
Though the fine was triggered by Allstate's recent efforts to drop the wind and hail coverage of longtime customers who should be protected by state law, the fine technically was levied on the company as a result of a flawed property-inspection process that was supposed to determine whether homes were occupied or being rebuilt.
Last year Allstate dropped 4,772 customers after conducting drive-by inspections of 40,500 homes in the New Orleans area that averaged about a minute a home. Allstate said it dropped the policies because the inspections revealed that the homes were unoccupied or not being repaired. Within a few weeks, 588 people filed written complaints with the Insurance Department saying they were in fact living in the home or rebuilding.
The department ordered that Allstate temporarily reinstate all policies and redo the inspections, with documentation. How many of the 4,772 customers ultimately qualified to keep their reinstated insurance coverage is unknown, but 552 of the 588 people who complained were found to have been improperly terminated and were reinstated.
When the department forged an agreement with Allstate on the issue in March, Donelon reserved the right to impose sanctions. As the department began investigating a new round of complaints that began just a month later with Gretna homeowner Michael Scioneaux, Donelon decided he needed to do so.
Dropped after 31 years
Scioneaux had been insured by Allstate for 31 years at the same home and never made a claim outside of Hurricane Katrina, but he got a letter in April saying his wind and hail coverage would be dropped because he had been with the company for less than three years.
The letter made no sense because Louisiana has a law that says once a customer has been with an insurance company for three years, it's very difficult to drop them. Customers can be dropped only if they stop paying their bills, make excessive claims for non-"act of God" events such as hurricanes or tornadoes, commit fraud, or unless the company can prove to the Insurance Department that it risks going bankrupt if it keeps them.
But several years earlier, Scioneaux had taken advantage of a good-credit discount that Allstate offered. Unknown to Scioneaux, Allstate rewrote his policy from letterhead that said "Allstate Insurance Co." to stationery that said "Allstate Indemnity Co." to process the discount.
In the April 2007 letter, Allstate now said the May 2004 change meant that Scioneaux was a new customer whose wind and hail coverage would be dropped in June. Scioneaux said he was not informed of any such risks when he accepted the discount offer and that the shift amounted to a bait-and-switch for the company's benefit. Allstate has been under a corporate mandate to reduce its exposure in coastal areas.
Scioneaux was overjoyed at the news that his policy would be reinstated. "I just heard I won. I'm in a state of shock," he said Wednesday.
Since the summer, Scioneaux has been forced to buy his wind and hail coverage from Louisiana Citizens Property Insurance Corp. But because he was angry that Allstate cut the most important part of his policy, he moved to Louisiana Farm Bureau Mutual Insurance Co. for his fire, theft and liability coverage as payback, and cut Allstate out of the deal so it would be unable to earn easy premiums.
Even though Scioneaux says he has no love for Allstate, he said he plans to return to the company because it's a better deal than a split policy. "I'm really not in a position that I can pick and choose. I need to take the best coverage and the best price to protect me and my family and our biggest investment: our house," said Scioneaux, who is also personnel director for Jefferson Parish.
For now, Scioneaux plans to celebrate. His Allstate agent, a friend who also lost his wind and hail coverage, called and invited him out to dinner Friday night. Scioneaux also will be having a celebration lunch with two other dissatisfied Allstate customers whom he met during the course of complaining to the Insurance Department.
"We're comrades in a cause," he said. "I never thought I would feel so happy about being able to go back to a company where I'm going to have to pay an expensive policy."
Unknown number affected
About 21 people in Scioneaux's situation have complained to the Insurance Department, but it is not known how many customers of Allstate or Encompass, the brand of Allstate insurance sold by independent agents, were affected. Allstate's news release says "a few hundred" are in the group.
According to the terms of the agreement, Allstate must give the Insurance Department a list of people like Scioneaux who were dropped within seven days and send customers an offer to come back within 30 days. That offer will include wind and hail coverage, but it will carry a 5 percent storm deductible, as all Allstate policies have done since June. The company must "take all reasonable and necessary efforts to contact each customer directly," and within 90 days, it must give the Insurance Department a list of how many of those people opted to come back.
Not everybody was impressed with the settlement.
Bob Hunter, director of insurance for the Consumer Federation of America, said a $250,000 fine for a company that earned $4.6 billion in net income last year is negligible. "The fine, for Allstate, is chump change. It's a cost of doing business," he said.
Hunter, who is originally from New Orleans and who served as insurance commissioner in Texas in the early 1990s, said Louisiana needs to make sure Allstate doesn't pass on the cost of its fine to customers because the state doesn't have a law barring companies from throwing the cost of fines into rate filings.
Wednesday, February 20, 2008
Robin' Hood of Support
Blogs are touted as the savior of democracy – a voice for the people, a place where our cherished freedom of speech enjoys the freedom of information.
…and, by the way, did I mention the bridge I’ve got for sale up in Brooklyn?
Blogs are in the information business – news you can use but news that can use you, too.
Last week blogs were big news. The defense team for the King of Torts, indicted Mississippi attorney Richard “Dickie” Scruggs, cited the unfavorable environment created by blogs in the Motion for Change of Venue.
The named blogs responded with a “moment of silence” and noticeable absence of some of his most vicious critics. However, it wasn’t long before they were back in business -feasting on Mississippi Attorney General Jim Hood with a side dish of Scruggs and the others for desert.
Hood is a state-wide elected official and his conduct is fair game for public conversation – but this game was anything but fair. Although he recently won reelection by a larger percentage of vote than any other candidate, few of his supporters comment on these blogs. Understandably so - take a look at the titles of these posts: AG Jim Hood Goes on Offense…and Fumbles the Ball; What's the Name for Hood Posts; and Hood Pours Gasoline, Strikes Match, and Sets Self on Fire.
I don’t know who picked up the tab for this feast but I know who paid the price – the people on the Coast – particularly those with State Farm claims unsettled. Banned from one blog and then another, and threatened by yet a third, robbed Hood of his strongest supporter and those who read these blogs of a balance view.
I came to offer Promise – for every voice to be heard. Meet bellesouth a fearless fighter for the people on the Coast – a diva of a defender with a sack full of rock solid fact and a spirited opinion up against a Goliath of critics who turned on her when they had nothing of substance to throw back.
(Note from Sop: To the extent this intersects with insurance we are allowing some Jim Hood discussion. We have begun the process of contacting the Office of the Mississippi Attorney General in hopes Mr Hood will comment to the extent he can on what his office is doing for us on these insurance issues. Given the pilloring he has taken, unfairly in certain respects in our opinions, we intend to provide a blog outlet that will simply allow him to present a differing point of view, just as we welcomed the Rimkus Engineer's viewpoints on our Aiken threads.)
Also a quick hello to Mr CLS and our thanks for reading us. - sop
Tuesday, February 19, 2008
State Farm Cancels 50,000 Florida Policies
Here you go pardners, the private insurance industry doesn't want our coastal wind business and they don't want a federal solution 'cause it might cut into their profits from offshore reinsurance. So what do they do to keep the pressure on? They cancel you out like State Farm just did in Florida and New York. We got this from our friends in Florida at the Herald Tribune:
HURRICANE INSURANCE
State Farm dumps 50,000 statewide
Longtime State Farm customer John Spencer is not wanted any more.
He is getting dumped, one of 50,000 coastal Florida homeowners whose hurricane coverage will not be renewed by State Farm this year.
"It just irritates you that you get canceled, and it makes you nervous," said Spencer, whose policy on his Englewood home expires several weeks before the start of the 2008 hurricane season.
An estimated 7,500 customers in Sarasota, Manatee and Charlotte counties will be dropped by State Farm, Florida's largest private homeowners insurer.
Many will wind up with windstorm coverage at Citizens Property Insurance Corp., the state-run insurer that is one of the few options for insurance near the coast.
For some of them, there could be a silver lining.
State Farm is among the priciest insurers for coastal properties. Citizens, after rolling back one rate hike last year and freezing rates through 2008, could be a cheaper alternative.
Punta Gorda Isles homeowner Gerald Crowley expects to switch to Citizens when his State Farm policy expires in late March.
His premium will drop about $600 from the current $3,600. But he is still not happy about being dumped.
"It's the principle of the thing," he said. "I can afford what they wanted to charge."
Sarasota insurance agent Al Malins said some private companies are writing new policies along the coast and may accept customers from State Farm.
"People certainly have options," he said. "It pays to do some shopping around."
Norm Harte, also a Punta Gorda Isles homeowner, has been searching for new coverage since he got his cancellation notice last month.
"We've pursued Citizens and others, but the coverage they are offering is pretty awful," he said.
He may save a modest amount of money by going with Citizens, but it will come in part by reducing his insured value from $350,000 to $305,000 and eliminating such coverages as a pool cage.
Harte thinks the state should block insurers from "cherry picking," or getting rid of their riskiest customers.
"If State Farm or any insurance company doesn't want to do the whole game, pull their license and find somebody else to do it," he said.
Many property insurers have trimmed their Florida exposure since the 2004-2005 hurricane seasons, which caused $37 billion in insured damage.
Allstate, Nationwide, USAA and Tower Hill are among the major players that have pared down.
State Farm stopped writing new business in some coastal counties years ago, but this was the first time the company decided it needed to drop policies, said spokesman Chris Neal.
"We kind of managed it through attrition, but we came to the point where that just wasn't working for us anymore," he said.
The 50,000 nonrenewals represent about 5 percent of its 1 million homeowners policies in Florida.
State Farm began the policy cancellations last fall but was soon blocked by the Florida Office of Insurance Regulation. The original plan was to drop customers who lived within several miles of the coast or other bodies of water, while retaining any of those with other company policies, such as auto.
The insurance regulators objected to that practice. After reaching an agreement with OIR over who would be canceled -- along with promising a 9 percent rate cut -- State Farm began resending nonrenewal notices in January. That premium reduction followed an average 53 percent rate hike in 2006.
The company is now cutting all windstorm policyholders who live within one mile of the coast, regardless of any other coverage they have.
Those customers are getting at least 120 days of advance notice so they can find new coverage. Timing can be an issue -- some insurers, including Citizens, will not quote a new policy more than 30 days before it takes effect.
Pressure from the state to lower insurance rates is driving companies to reduce exposure, Neal said, as they balance their ability to pay claims when a hurricane hits.
"You've got two choices: raise rates or lessen your exposure," he said. "Our choice here was to lessen exposure. Being closer to the water presents the highest risk. By nonrenewing 50,000 homes closer to the water, it takes a significant amount of exposure away from the company."
Spencer, a State Farm customer in Florida and elsewhere for 30 years, hopes to find wind coverage from someone other than Citizens.
"They are just dumping us into the Citizens pool," he said. "It is not as good a coverage. If they are just dumping liability back to the government, why not just have government insurance?"
Malins said his agency tries to avoid putting customers into Citizens because they may later become "take-out" policies by other carriers.
Citizens was criticized for poor customer service after the 2004 hurricanes, but regulators and others say it has improved.
"You have to give them credit for trying to act more like an insurance company," Malins said.
Some homeowners with other State Farm lines, such as auto, are thinking about taking that business elsewhere.
Citizens does not offer auto insurance, and those homeowners could miss out on multi-line discounts they now enjoy.
State Farm, Florida's largest auto carrier, expects some of those customers will leave.
"It would be naive of us to think we won't lose some of our auto business because of the nonrenewals," Neal said.
Sunday, February 17, 2008
Gene Taylor to Speak on Insurance Reform
There has been an advertisement run in the print editions of the Sun Herald on Gene Taylor conducting an Issues + Answers lecture sponsored by the University of Southern Mississippi Gulf Park Campus on Friday, February 29, 2008 at the Advanced Education Center auditorium.
Thanks to one of our readers, I was emailed a link to the University press release and I am happy to pass it along to all so interested. Considering the other recipients listed in the address header I am honored Ida thought enough of this blog to pass me the good word.
I will be in attendance and hope we pack the house on the 29th.
sop
Friday, February 15, 2008
The Mississippi "R" Factor Part 2
I've noticed that when solutions to this insurance mess are offered it is one political party that is doing the offering. Outside of a few Democrats like US Senator Christopher Dodd the Republican party is the overwhelming choice for discriminating big business and insurance political donors.
Such must certainly be the case here in Mississippi as we found this Clarion-Ledger story concerning Phil Bryant's State Senate Insurance Committee most disturbing. Lt. Governor's Bryant stated campaign goal of continuing the coastal rebuilding efforts certainly are taking a back seat to his service to monied insurance interests.
No offense to Senator Clark but if actually thinks anyone believes that load of dung he shoveled then I have some waterfront in the New Mexico I'd like to sell him.No Katrina-related insurance legislation will be taken up by the Senate Insurance Committee this year, chairman Sen. Eugene Clarke said Thursday.
Clarke, R-Hollandale, said he needed a year to get acclimated to leading the committee before passing any bills.
"I feel for people on the Gulf Coast, but we've got totally new leadership in both chambers," he said.
Clarke's decision has soured some Gulf Coast senators, though, who say nothing has been down two and a half years after Hurricane Katrina flattened the southern part of the state.
Sen. David Baria introduced seven pieces of insurance reform legislation this session, but he said Clarke told him Thursday they would all die in committee.
"It's upsetting because this is the primary reason I decided to run for the Legislature - to do something about insurance," said Baria, a freshman lawmaker who defeated Republican incumbent Sen. Scottie Cuevas in the November election."While I understand (Clarke) is new... we can't wait any longer to do something about this issue."
The two pieces of legislation the Bay St. Louis Democrat said he was most interested in seeing get to the floor included:A bill to codify a premium payer's Bill of Rights and attach it to policies, as well as include plain-language exclusions and eliminate concurrent cost exclusions. He filed two versions of the bill and one would prohibit insurance companies from contributing to anyone running for commissioner of the Department of Insurance.
A bill that would offer apply a premium reduction in the private sector to those who build a "fortified" home - similar to regulations under the so-called Windpool.
Clarke said he was going to spend the "off season" studying up on the legislation.
"We want to take care of consumers," he said.
The comments to the Clarion Ledger story tell that tale of Senator's Clark's continued study of an issue that is now almost 30 months old.
No offense to Sen. Clarke, but perhaps the Senate leadership should have asked him if he felt comfortable chairing a committee related to insurance issues BEFORE appointing him to chair the Senate Insurance Committee. I bet the beleagured folks on the Coast would have appreciated that. Why is it that after almost every article I read about our Legislature I find myself having to take deep breaths and rub my temples? I would hate to assume that he was placed there because he would be willing to block anything the insurance companies didn't want becoming law.
or this one
Thanks Mr. Clarke! The coast gets shafted because you need on the job training.
Senator Clarke is doing as he is told which is why I place the blame for this inaction on his boss Lt Governor Bryant. The Mississippi Democrat party appears in complete disarray so I doubt they capitalize on the insurance "R" factor to score political gain. I hope everyone that supported Mr. Bryant and Mr. Chaney last November and who now pay much higher insurance are taking notes.
sop
The Mississippi "R" Factor Part 1
We have more insurance news out most of it involving the State of Mississippi. As I noted yesterday the contrast between Commissioner McCarty and the Republican Party in Florida and Commissioner Chaney and the Republican leadership in Mississippi is striking and very unfavorable to our leadership here. Today we are greeted with this news story in the Sun Herald on the Mississippi Windstorm Underwriting Association:
Homeowners insurance has been that dirty little secret buried in the howling wind insurance storm. Coastal consumers are routinely finding their wind excluded homeowners policy costs as much today as their wind included homeowners policies before Katrina. I have not heard of increased fire, theft or liability risk here on the coast since the storm. Curious.Residential policyholders have been shocked by significantly higher premiums in their wind-pool renewal notices.
Wind-pool board members approved policy changes, effective Oct. 1, that mean higher rates for the majority of policyholders who stick with a 2 percent hurricane deductible. A Sun Herald reader alerted the newspaper to the policy changes Thursday.
Wind-pool board member David A. Treutel Jr., who is from the Coast, said the change was in error. The board, he said, was trying to give the best wind discount possible while keeping options simple. He said the error was brought to the board's attention in January and members voted unanimously to correct it. A correction should apply retroactively to rates charged since Oct. 1.
"The direction from the board was to fix it," Treutel said. "That wasn't intended."
As of now, policyholders who used to have $1,000 or $2,500 deductibles for unnamed storms will feel a pinch unless they raise their named-storm deductibles. Even then, their rates might still increase even though their out-of-pocket expenses will be higher after a catastrophe.Such was the case for Rex Chastain's family. Chastain had hoped for some insurance relief in 2008, but instead finds his family "insurance poor."
Hurricane Katrina forced the Chastains, along with thousands of other South Mississippi residents, into the state wind pool, where residential rates jumped 90 percent in 2006. The wind pool is the insurer of last resort for 36,000 South Mississippians, who must carry a separate private policy to cover fire, theft and liability.The Chastains' total homeowner insurance bill jumped 147 percent. (Emphasis mine)
We were also greeted with this story on David Baria and his attempts to pass some common sense legislation in the Mississippi Senate dealing with insurance.
Sen. David Baria has filed seven Hurricane Katrina-related insurance-reform bills, but on Tuesday legislators will finalize the list of measures that stay alive, and his are in danger of dying without a vote.Indeed we agree with Senator Baria on SB 2432 and SB 2165; these laws should be a no brainer. Insurance impacts everyone in the state but it has impacted coastal residents in an outsized way, which in turn has greatly elevated the level of awareness these issues here. The real problem in my opinion lies with Lieutenant Governor Phil Bryant and his choices for the insurance committee, which he evidently stacked with pro insurance legislators.
The first-term legislator, a Democrat from Bay St. Louis, attended the Senate insurance Committee meeting Thursday briefly to see if any of his bills were up for discussion, but was surprised when he found they were not.
Baria has filed a "Policyholder's Bill of Rights." The measure would put the burden of proof on the insurance companies when there is a dispute over whether a claim is covered in a policy. The House Insurance Committee approved a version of the bill Wednesday, allowing it to move forward.
Baria said it's surprising two of his Senate bills, which he considers minimal changes, haven't made it out of committee. Senate Bill 2432 would make it mandatory for insurers to attach a list of a policyholders' rights to each homeowner's policy. Senate Bill 2165 would help homeowners who use stronger construction methods get discounts on the rates they pay.
"To me, both of those bills should be no-brainers," Baria said.
Of the Senate Insurance Committee's 13 members, only three are from South Mississippi - Watson, Billy Hewes, R-Gulfport, and Debbie Dawkins, D-Pass Christian. Eugene S. Clarke, R-Hollandale, chairs the committee, which is made up of eight Republicans and five Democrats.This is R factor is at work. How quickly Mississippi Republicans have forgotten the people who elected them to office.
Most of the Legislature's post-Katrina insurance reforms aimed at coverage offered through the private sector have failed. The Legislature last year approved a bailout for the state wind pool, which is the insurance of last resort for those who can't get private wind coverage.
sop
Thursday, February 14, 2008
Insurance News Today
There are two news stories in today's Sun Herald that are well worth pointing out. The first deals with the House Insurance Committee's passage of a Policyholder's Bill of Rights, prompted by the treatment of consumers here on the coast after Hurricane Katrina.
Long Beach resident Kevin Buckel lost his house on Russell Avenue to Katrina, but was originally paid only $1,000 by Nationwide, but the company later settled a lawsuit with him. Buckel told the committee that putting the burden of proof on the insurance company is the most important part of the Policyholder's Bill of Rights.
"When you are denied a claim, the insurance companies would be more likely to settle with homeowners if they can't prove their case in court," Buckel said.
I have not read the bill but I take Mr Chaney's reservations concerning it to mean it must favor consumers over insurers.
The second story should come as no surprise that private insurers will continue to increase the pressure by economic strangulation of the coast enabled by former insurance agent turned inusrance commissioner Mike Chaney. I find the contrasts between Mr Chaney and Mr McCarty in Florida most telling as I do the timid reactions of Mississippi politicians in general to this issue in huge contrast to those in Florida.
Mississippi Insurance Commissioner Mike Chaney said some major insurance carriers have indicated they may no longer renew wind coverage for customers in South Mississippi.
"If they quit writing wind for existing customers, that's really going to put more pressure on the economy," said Chaney, who added that he is working to keep private carriers in the six southernmost counties and bring in new business.
He hopes enforcement of enhanced building codes, coupled with other measures his office is pursuing, will improve the market.
Is it me or were the new buillding codes passed after the storm in late 2005 or early 2006? Perhaps it's time Mr Chaney quit hoping and instead champion the people who elected him to office. Frankly I would personally never sign up with a private insurer for wind coverage, as it is a waste of money buying a policy that does not pay on wind damaged coastal properties. Like my home before the storm my rebuild will be in the wind pool which did pay on their policies as a rule.
sop
Nationwide on Your Side? Nope
Any company that would screw an old lady certainly has no problems messin' with younger folks. Keep that chair pulled up as these videos illustrate why folks like Senator Chris Dodd and Richard Shelby live by "Show me the Money". If you is common folk and got no money then you don't count like their friends in big insurance.
Tuesday, February 12, 2008
Nationwide: Not on Your Side?
Pardners when this Cowboy says big insurance will go to great lengths to screw the elderly for a buck he means it! Pull up a chair and listen to this poor ole woman's nightmare dealing with her own insurance company Nationwide Insurance. I hope insurance industry waterboys like Senators Chris Dodd and Richard Shelby are proud of themselves and their service to big insurance. Bless their hearts their mommas must not have taught them right from wrong when they was growin' up.
Wednesday, February 6, 2008
Florida Gets a Big Fat F
Florida gets an 'F' for insurance system
from the South Florida Business Journal
February 6, 2008
Florida has one of the least-effective property and casualty insurance systems in the country, a new study that gave Florida and four other states an "F" grade said.
The joint project of the Heartland Institute and the Competitive Enterprise Institute rated all 50 states on nine criteria, including how prominent the states' roles are in the auto and home insurance markets, and the concentration of insurance companies writing policies in a particular state. California, Massachusetts, North Carolina and Texas joined Florida in getting an F. Connecticut, Idaho, Illinois, Utah and Vermont got A grades.
Florida scored at or above average in seven of the nine categories. But Florida had the worst rating in the residual homeowners category, which measures how much of the market is served by government-provided insurance. Jacksonville-based Citizens Property Insurance Corp., the state-run insurer of last resort, is No. 1 in statewide market share.
Florida also scored poorly in the regulatory environment category for having an outsized influence in the setting of rates.
I would love to see the formula. Florida is above average in 7 of 9 categories. But because the State Government holds a lot of the policies, they get an F. Apparently the fact that many insurers have not been interested in insuring Florida home owners does not matter. Amazing.
Texas, North Carolina, and California all have to deal with big natural disaster issues so I am assuming some form of state self insurance makes them a failure as well. Massachusetts probably banned personal property when Romney was governor in an effort to avoid paying out any insurance to anyone ever.
Saturday, February 2, 2008
Insurance firms set to stump up billions
Insurance firms set to stump up billions
2008-02-02
By Hu Yuanyuan (China Daily)Updated: 2008-02-02 08:57
Chinese insurers are expected to pay 3.52 billion yuan ($489 million) in damages to companies and people in central and eastern China as a result of the worst snowfall in almost half a century, the nation's insurance regulator said on Friday.
What is odd is that the insurers appear to be paying claims to people who did not even have insurance. Apparently they view their work as a service to their country. What an odd concept.
Passengers walk past a row of Chinese soldiers near the railway station, in China's southern city of Guangzhou, on February 2. China warned the worst was not over in its national weather crisis as desperate crowds trying to get home jammed transport hubs and others braved the frigid cold without power or water.
Thursday, January 31, 2008
How the Other Side Lives
…other side of the Pacific that is.
Although large natural disasters outside of the United States are often associated with “less developed” nations needing our help, the reality is that a variety of disasters do strike within the 1st world economies. The European heat wave of 2003 has been estimated to have killed 14, 800 Frenchmen alone, and the Kobe earthquake of 1993 killed 5,100 people in an area of the country thought to be relatively safe from severe earthquakes.
I did run across an interesting piece that described US Government issued flood insurance policy with the earthquake insurance issued by the Japanese government.
“Insurance Issues of Catastrophic Disasters in Japan: Lessons from the 2005 Hurricane Katrina Disaster” written by Hiroaki Tsubokawa. 
What is interesting is that there are so many parallels between the two countries responses to the threat of large scale catastrophe.
Both countries offer government funded catastrophe insurance, and in both countries insurance is taken only by a limited group of people.
In the US, the National Flood Insurance Program (NFIP), 41% (2,181,930) of policies are issued in Florida (as of April 2007), followed by Texas, and then Louisiana. Given that Florida has 7.05 million households (per the US census), even if only half of them are non-renters, that would put flood insurance ownership by home owners at 62%.
In Japan, the number also varies by region, but nationwide 38% of insurance policy holders have earthquake insurance.
In both countries the lack of participation drives up the cost of insurance. At the time of this study the average NFIP annual premium was $438: very high with respect to its limited benefits. One reason (though not the only one) benefits are limited is that it helps keep the premiums down. Japan actually caps the total amount that will be paid out across the country and in any case they limit the payout on earthquake insurance to ½ the value of the underlying fire insurance policy. What is also interesting is that after the Kobe earth quake, they had a large battle between the insurers and insured because fire insurance did not cover earthquake damage: yet many building burned down as a secondary effect of the earthquake.

Much of the Japanese reaction was somewhat similar to the US. They discussed more national funding of insurance policies to take care of disaster situations, and they became much more interested in accurately mapping out a natural hazard map. It is not clear from this paper that they did anything much more concrete.
Wednesday, January 23, 2008
From Insurance Regulator to Insurance Lobbyist: Incest in the System
It turns out George Dale is not the only local insurance commissioner going straight from his elected office to work in the Insurance Industrial Complex. Strangely Adams and Reese was silent on their hiring of Robert Wooley, the first insurance commissioner in Louisiana in several years not in jail because of corruption. This quote from the story sums up why none of the authors of this blog trust our insurance regulators and is the basis for our opinion that federal oversight of this industry is well past due:
"Bob Hunter, a former Texas insurance commissioner who is director of insurance at the Consumer Federation of America, said that Dale's new job at a law firm that represents so many insurance interests is another unfortunate tale of regulators caring more about the industry than the people who elected them.
"Nothing surprises me any more. The insurance industry and the regulators are so intertwined. We've had now two presidents of the NAIC (National Association of Insurance Commissioners) go directly to lobbying jobs with the insurance industry, and we've had so many former insurance commissioners head off in that direction, it's disgusting. How can the public trust state regulation with all this going on?" Hunter asked."
sop
Monday, January 21, 2008
Bad Faith Claims Handling: The New Norm for Big Insurance
Folks we got sold a pig in the poke with tort reform as our legislators just give them crooks in Gucci suits a bigger club to hit the common man right in the head. That's right boys and girls, insurance companies will deny legitimate claims knowing most folks won't fight 'em but occasionally people do like this Tow Truck outfit. So pop some pop corn, pull up a chair and see if Pink Pigs Fly. This video is dedicated to this Cowboy's favorite corporate insurance lawyer in Portland Oregon, Mr. David Rossmiller.
Like this story says and Sop can personally vouch, there is no dollar amount too low for these crooks to try and screw you. And don't you know that corporate insurance lawyers love making big fat fees fightin' for a year over $3000. If you want to be paid fair like, be prepared to sue!